E-World

E-World

Updates

We look forward to E-world 2027!

Decision Trees will once again be at E-world energy & water in Essen in 2027. From 16 February 2027, we look forward to welcoming you at our booth 3F134. begrüßen zu dürfen.

Whether battery storage, renewables, gas storage or flexible supply contracts: we will show you how stochastic optimisation helps you recognise the value of flexibility and use it in day-to-day trading.

Would you like to book a meeting in advance? Just get in touch.

Your contact:
Gerhard Hundsberger
E-Mail: office@dtrees.com

Looking back: E-world 2026

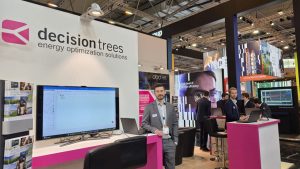
Three days of exciting discussions, inspiring encounters and great reunions – E-world 2026 in Essen was a great success for us.

Many of the conversations at our stand focused on market optimisation of battery storage and renewable energy. The strong interest showed us how important intelligent optimisation of flexible assets has become for the energy transition.

Many thanks to everyone who visited us! We look forward to the follow-up conversations and to developing our shared ideas further.

Market optimisation of battery storage and renewable energy

As the share of renewable energy grows, price volatility on power markets increases – and with it the value of flexibility. Battery storage and flexible generation assets can make targeted use of this volatility. The key is to make the right marketing decisions at the right time and across all markets.

Our services:

  • 24/7 cross-market management of battery storage and renewables
  • Automated cross-market optimisation across day-ahead, intraday and balancing markets
  • Consideration of technical constraints such as state of charge, cycles and degradation
  • Preparation of optimal energy bids

Your benefit:
Maximum revenue from flexibility, while operating efficienty and managing market risks transparently.

In the rapidly changing gas markets, the market-based and stochastic evaluation of natural gas storage, contracts and procurement portfolios is becoming increasingly important. Stochastic optimisation makes it possible to model market fluctuations. Our solutions include the following areas:

Optimisation of gas procurement portfolios

  • Decision support for structured gas procurement on forward and day-ahead markets
  • Flexibility to cover sales volumes is ensured through flexible contracts or gas storage, even in partially illiquid markets.
  • Representation of the full complexity of procurement portfolios: gas- and oil-indexed supply contracts, gas storage, transport constraints, different market areas, etc.

  • Our solution: optimisation using stochastic market prices and sales load profiles, together with risk-adjusted management of open positions on the forward markets

Valuation of gas storage and flexible gas supply contracts

  • Intrinsic and extrinsic valuation of gas storage and flexible gas supply contracts with highly complex volume constraints and energy price formulas

  • Modelling and scenario generation for forward and day-ahead natural gas markets

  • Estimation of volatility, mean-reversion and correlation parameters based on historical price movements
  • Modelling of the real-world marketing of storage and contracts – joint representation in spot and forward markets
  • Dynamic hedging – risk-free profits can be realised by rebalancing the forward market portfolio.
  • Our solution: joint stochastic optimisation of spot and forward market management across all paths of a scenario tree


Your benefits from stochastic optimisation 

The intrinsic value of a flexible asset, such as a gas storage facility or a gas supply contract, is the value that can be achieved at current market prices. Thanks to its flexibility, the future value of the asset that can be generated from changes in spot and forward market prices is considerably higher. This extrinsic value is determined using stochastic optimisation. This can be done for individual assets as well as for entire procurement portfolios.

In addition to the intrinsic and extrinsic valuation of assets or asset portfolios, stochastic optimisation is used to make more efficient decisions in the day-to-day management of gas storage, gas contracts or procurement portfolios. This covers both day-ahead asset management and trading on spot and forward markets.

In practice, the stochastic optimisation of natural gas portfolios has been shown to deliver higher profits or lower procurement costs.

The following steps are carried out for the stochastic valuation and optimisation of gas industry assets:

  • Estimation of the volatility, mean-reversion and correlation parameters of all market prices (day-ahead and forward)
  • Scenario generation for day-ahead market prices
  • Scenario generation for forward market prices (taking into account correlations between forward market products and with the day-ahead markets)
  • Scenario generation for load profiles
  • Joint stochastic optimisation of gas industry portfolios
  • Determination of profit distributions or procurement cost distributions
  • Determination of shadow prices (value of gas in future management periods)
  • Derivation of trading and management decisions
OFFICE
MUNICH

Konrad-Zuse-Platz 8
D-81829 München

Tel.: +49 89 207042 284
Fax: +49 89 207042 288

office@dtrees.com

OFFICE
ST. GALLEN

Zürcherstrasse 240
CH-9014 St. Gallen

Tel.: +41 71 313 05 55
Fax: +41 71 313 05 01

office@dtrees.com

TOP NEWS

Decision Trees freut sich darauf Sie ab 16. Februar 2027 an unserem Stand auf der E-World in Essen begrüssen zu dürfen.

© Decision Trees GmbH – All rights reserved

dtrees-logo-footer
Nach oben